

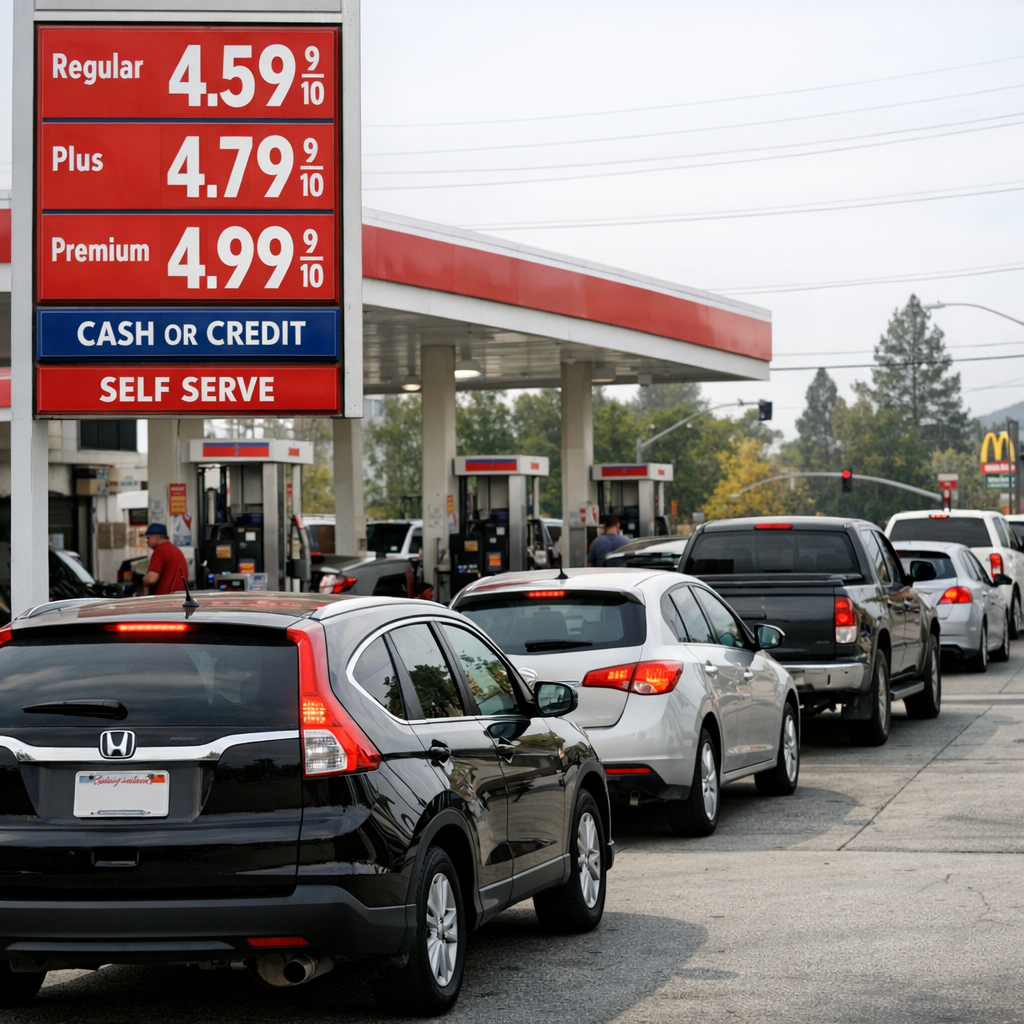
As the nation grapples with economic challenges, recent data indicates a significant rise in inflation and gas prices, affecting households across the country.
Inflation on the Rise
In April, inflation surged to 3.8%, marking the highest rate in three years. This uptick is largely attributed to the ongoing military conflict with Iran, which has disrupted global oil supplies and driven up energy costs. The closure of the Strait of Hormuz has been a critical factor in this disruption.
Gas Prices Soar
Consequently, gas prices have climbed sharply, with the national average exceeding $4.50 per gallon. Some states are experiencing prices above $5, placing additional financial strain on consumers. This increase has led to a decline in consumer confidence, as many Americans find their incomes are not keeping pace with rising costs.
Impact on Households
The combination of higher inflation and escalating gas prices is affecting daily life and financial stability. Many households are adjusting their budgets, cutting back on discretionary spending, and seeking ways to mitigate the impact of these economic pressures.
Looking Ahead
As the situation evolves, it remains crucial for policymakers to address these economic challenges and implement measures to stabilize the economy. Consumers are encouraged to stay informed and consider financial strategies to navigate this period of uncertainty.